How to Find Annual Income Basics
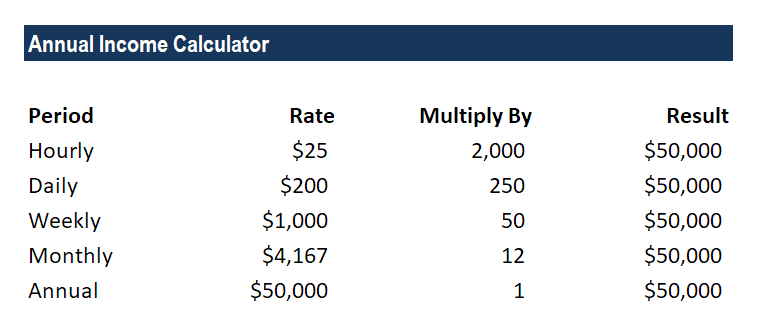
Table of Contents
- Understanding Annual Income in the Gig Economy
- Tracking and Calculating Annual Income from Gig Work
- Implications of Annual Income on Taxes and Benefits for Gig Workers
- Strategies for Managing Annual Income in the Gig Economy
- Conclusion
- Calculating Spousal or Partner Income
- Calculating Combined Income from Multiple Earners
- Tax Obligations and Benefits, How to find annual income
- Outcome Summary: How To Find Annual Income
- FAQ Insights
Understanding how to find annual income is a crucial aspect of financial planning and management. Delving into this topic allows individuals to grasp a solid grasp of their financial situation.
This guide offers a comprehensive look at the various aspects that can help you calculate your annual income, including reliable sources, income verification, and calculations for variable income and irregular payments.
Understanding Annual Income in the Gig Economy
In today's gig economy, many people earn a living by working multiple freelance jobs, driving for ride-sharing services, or participating in online marketplaces. The concept of annual income has become increasingly complex, making it difficult for gig workers to estimate and track their earnings. This is where understanding annual income in the gig economy comes, allowing individuals to make informed decisions about their finances and plan for the future.
The gig economy is characterized by short-term, flexible work arrangements that can be unpredictable and irregular. As a result, it can be challenging for gig workers to calculate their annual income. Unlike traditional employees who receive a steady paycheck, gig workers often work on a project-by-project basis, with varying payment structures and frequency.
Tracking and Calculating Annual Income from Gig Work
To effectively track and calculate annual income from gig work, it is essential to develop a system for recording and organizing income and expenses. This can include using accounting software, spreadsheets, or even a simple notebook to log income and expenses. Gig workers should also keep track of their payment schedules, including the frequency and amount of payments received.Here are some steps to follow when tracking and calculating annual income from gig work:
* Log every payment received, including the date, amount, and source of payment.
Implications of Annual Income on Taxes and Benefits for Gig Workers
The implications of annual income on taxes and benefits for gig workers are significant. Unlike traditional employees, gig workers are responsible for their own taxes, benefits, and expenses. This can lead to a complex and time-consuming tax filing process, as gig workers must calculate and pay their own taxes, including self-employment taxes.Here are some key implications of annual income on taxes and benefits for gig workers:
* Self-employment taxes: Gig workers are responsible for paying self-employment taxes, which include both the employee and employer portions of payroll taxes (15.3% for Social Security and Medicare, and 2.9% for Medicare).
Remember to keep accurate and detailed records of income and expenses to ensure accurate tax filing and benefit calculations.
Strategies for Managing Annual Income in the Gig Economy
There are several strategies for managing annual income in the gig economy, including:* Developing a budget: Create a budget that accounts for income, expenses, and taxes.
Conclusion
Understanding annual income in the gig economy is essential for gig workers to make informed decisions about their finances and plan for the future. By tracking and calculating annual income, gig workers can develop a system for recording and organizing income and expenses, and make informed decisions about taxes, benefits, and expenses. By developing strategies for managing annual income, gig workers can ensure financial security and stability in the gig economy.Calculating Spousal or Partner Income
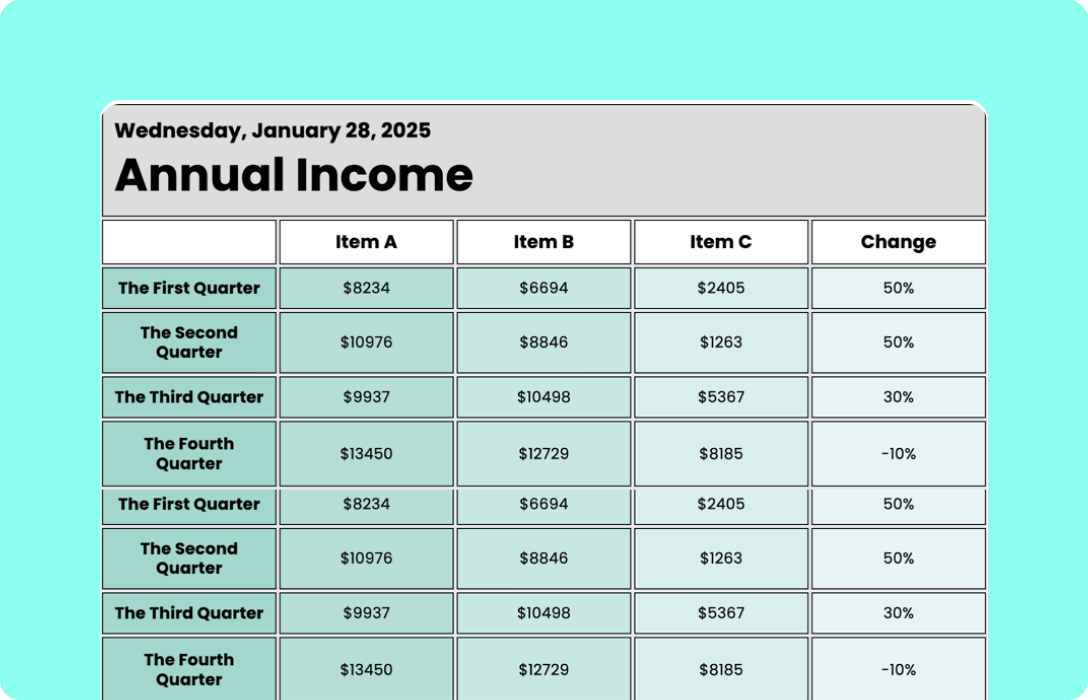
The income of your partner can affect your household's overall financial stability and planning. It can impact your ability to afford large purchases, save for the future, or pay off debts. Moreover, it can also influence your tax obligations and benefits, such as income tax, child support obligations, and social security benefits.
Calculating Combined Income from Multiple Earners
Calculating the combined income from multiple earners can be done by adding up the individual incomes of each partner. This includes wages, salaries, tips, bonuses, and any other forms of income.To do this, multiply the income of each partner by the number of pay periods they receive income, then add up the total income.
Example:
Partner A: $50,000/year (monthly pay of $4,167)
Partner B: $75,000/year (monthly pay of $6,250)
Total combined annual income:
Partner A: $50,000 x 12 = $600,000 (annual income)
Partner B: $75,000 x 12 = $900,000 (annual income)
Combined annual income: $600,000 + $900,000 = $1,500,000
In this example, the total combined annual income from multiple earners is $1,500,000.
Combined income = Income from Partner A + Income from Partner B
Tax Obligations and Benefits, How to find annual income
The income of your partner can impact your tax obligations and benefits, such as:- Joint tax filing: When filing taxes jointly, you and your partner are responsible for the total tax liability. This can result in higher tax deductions and lower tax withholdings.
- Tax credits: The income of your partner may affect your eligibility for tax credits, such as the earned income tax credit (EITC) or the child tax credit.
- Child support obligations: If you have children together, the income of your partner may impact your child support obligations, as the amount of child support may be based on the combined income of both parents.
- Social security benefits: The income of your partner may impact your social security benefits, as the full retirement age is different depending on the income level of your partner.
| Income Level | Joint Tax Liability | Eligible for Tax Credits | Child Support Obligations | Social Security Benefits |
| --- | --- | --- | --- | --- |
| Lower income | Lower tax liability | May be eligible for tax credits | Potential for reduced child support | May impact social security benefits |
| Higher income | Higher tax liability | May not be eligible for tax credits | Potential for increased child support | May impact social security benefits |
In this example, the income level of your partner can impact your joint tax liability, eligibility for tax credits, child support obligations, and social security benefits.
Outcome Summary: How To Find Annual Income
Overall, mastering the concept of annual income can have a significant impact on your financial decisions and stability. Therefore, it is essential to comprehend the different methods and factors that affect your annual income.
FAQ Insights
What is the impact of annual income on credit scores and loans?
Your annual income significantly affects your credit score and loan eligibility. A stable and high income can improve your credit score and increase your chances of getting approved for loans. Meanwhile, misrepresenting your annual income can lead to denied loan applications or higher interest rates.
Can I use pay stubs to verify my annual income?
Pay stubs can be used as a reliable source of income verification, but they may not accurately reflect your annual income. It is essential to consider other financial documents, such as tax returns and bank statements, to ensure accuracy.
How do I calculate my annual income from investments?
Calculating your annual income from investments involves considering factors like interest rates, market volatility, and time horizon. You can use a step-by-step guide to calculate your investment income, taking into account the performance of your investments over a specific period.
Leave a Comment
Comments are moderated before appearing. The data you submit is processed according to the Privacy Policy of blog.poolsupplies.com.